CORPORATE TAX
- Income Tax Deductions for Salary Payments Through Financial Institutions and Cashless Payment Instruments
- From YA 2028, it is proposed that a tax deduction on salary expenses be allowed only for payments made through financial institutions or cashless payment instruments prescribed under the Employment Act 1955, except for salary payment transactions by Micro, Small and Medium Enterprises (MSMEs).
- Tax deductions for expenses other than salary payments remain allowable regardless of payment method.
- Tax Deduction for Repayment of PTPTN by Employers on Behalf of Employees
- It is proposed that employers be given an income tax deduction for PTPTN loan repayments made on behalf of employees from 1 January 2027 to 31 December 2028, provided that:
- The employer must not require any payment from the employee in consideration for the PTPTN loan repayment made by the employer.
- The employee must be employed full-time.
- The employee must not be the business owner or have family ties with the employer.
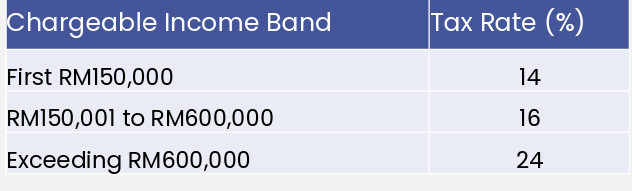
- Review of Income Tax Rates for MSMEs
- From YA 2027, income tax rates for qualifying Micro, Small and Medium Enterprises (MSMEs) are proposed to be revised as follows:
- Higher Capital Allowance Limits for Small Value Assets
- It is proposed that the capital allowance treatment for small value assets shall be enhanced as follow:
- Qualifying value per asset is revised from RM2,000 to RM3,000.
- Overall claim limit for companies other than MSMEs is revised from RM20,000 to RM30,000 for each year of assessment.
- Extension of Accelerated Capital Allowance (ACA) on Qualifying Capital Expenditure for Plant, Machinery and ICT Equipment
- The ACA on qualifying capital expenditure for plant and machinery, ICT equipment and software acquired from local manufacturer, will be extended from 31 December 2026 to 31 December 2030.
- Tax Deduction for Companies Implementing the Bakat MADANI Training Programme
- Tax deductions will be available to companies implementing the Bakat MADANI training programme from 29 June 2026 to 31 December 2030.
TAX INCENTIVES
- Tax Deduction for Automotive Vendors Relocating to Tanjong Malim
- To encourage wholly locally owned automotive vendor companies to relocate their operations to the Automotive Hi-Tech Valley in Tanjong Malim, a tax deduction will be provided for qualifying relocation costs of up to RM5 million.
- The deduction applies to expenditure incurred from 1 January 2027 to 31 December 2030.
- Income Tax Exemption for Shariah-Compliant Fund Management Services
- A resident company providing Shariah-compliant fund management services approved by the Securities Commission Malaysia (SC) will continue to enjoy a tax exemption, with the exemption rate revised from 60% to 40% of statutory income derived. The incentive will be extended for a further three years, covering YA 2028 to YA 2030.
- Tax Deduction for Sukuk Prisma Issuance Costs
- To strengthen Malaysia’s position as a global sukuk hub, it is proposed that an income tax deduction be granted on the issuance costs of Sukuk Prisma approved, authorised by, or lodged with the Securities Commission Malaysia (SC), from YA 2027 until YA 2030.
- Meanwhile, the existing tax deduction for SRI Sukuk issuance costs remains effective until YA 2027.
- Income Tax Exemption for SRI Sukuk and Bond Grant Scheme
- Income tax exemption will be granted for grants received under the Sustainable and Responsible Investment (SRI) Sukuk and Bond Grant Scheme effective from 1 January 2027.
- Tax Deduction for Contributions to Public Universities
- Contributions to public universities by members of the public, including alumni and the corporate sector, will qualify for an income tax deduction of up to 10% of aggregate income.
- Tax Deduction for Food and Equipment Contributions to Dapur Siswa MADANI
- A tax deduction will be provided to parties contributing food and equipment for the Dapur Siswa MADANI programme from 1 January 2027 to 31 December 2030.
- Extension of Tax Incentive for Individual ECF Investors
- To further support alternative financing and attract more individual investors in start-up companies and Micro, Small and Medium Enterprises (MSMEs) through Equity Crowdfunding (ECF) platforms, it is proposed that the tax incentive be extended for four years, from 1 January 2027 to 31 December 2030.
- Extension of Tax Incentive for Angel Investors
- The tax incentive for angel investors in technology start-up companies at the pre-seed and seed stages will be extended from 31 December 2026 to 31 December 2030.
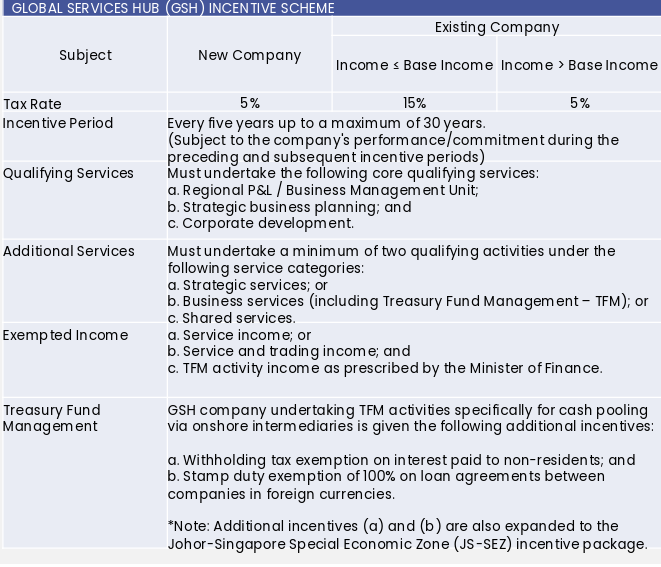
- Enhanced Global Services Hub Income Tax Incentives
- For applications received by the Malaysian Investment Development Authority (MIDA) from 1 January 2027, it is proposed that the Global Services Hub (GSH) tax incentives be revised as follows:
- A new company is a company that has not carried out GSH or Principal Hub (PH) activities.
- An existing company is a company that has been previously approved for the GSH or PH incentives and will undertaking additional new services for an extension application.
- The base income for an existing company is the average income for the last 3 years.
- Full Income Tax Exemption for Malaysian Shipping Companies
- Full income tax exemption for Malaysian shipping companies from YA 2027 until YA 2036, subject to the following conditions:
- Strategic management and effective control are implemented in Malaysia;
- Annual operating expenditure in Malaysia of at least RM250,000 for each Malaysian ship; and
- Employ at least 4 Malaysian citizens with an average monthly salary of RM15,000 for each Malaysian ship.
- Extension of Tax Incentives for Organising International Incentive Trips, Conferences and Trade Exhibitions
- It is proposed that the 100% income tax exemption on statutory income for companies, associations or organisations organising qualifying international incentive trips, conferences or trade exhibitions in Malaysia be extended for 3 years, from YA 2028 to YA 2030.
- The organising companies, associations or organisations must be certified by the Ministry of Tourism, Arts and Culture, and the events must meet the applicable annual foreign-participant threshold:
- Incentive groups: at least 1,500 foreign participants.
- Conferences: at least 2,000 foreign participants.
- Trade exhibitions: at least 3,000 foreign participants.
- Johor-Singapore Special Economic Zone (JS-SEZ) Incentive
- Under the Single Family Office (SFO) Scheme, a single family can manage its funds in Malaysia and enjoy zero tax on qualifying income for up to 20 years.
- A Multi-Family Office (MFO) model will be introduced in Forest City, allowing licensed fund managers to provide services to multiple families, including those with approved SFO funds.
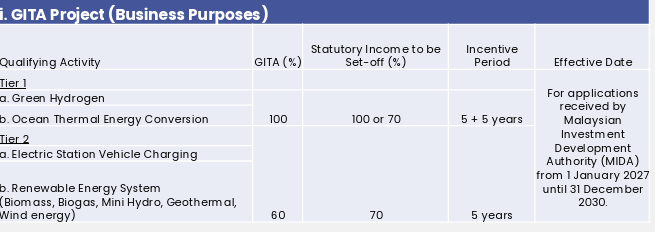
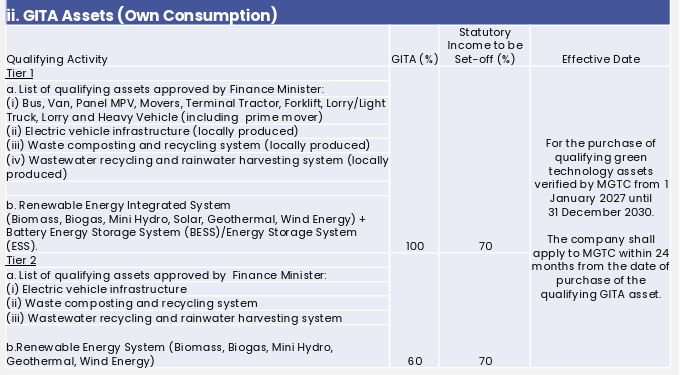
- Enhanced Green Technology Tax Incentive
- In line with the aspiration for sustainable national energy transition and net zero carbon emission by 2050, it is proposed that the Green Technology Tax Incentive be reviewed as follows:
- In line with the aspiration for sustainable national energy transition and net zero carbon emission by 2050, it is proposed that the Green Technology Tax Incentive be reviewed as follows:
PERSONAL TAX
- Increased Tax Relief for Individual and dependent relatives
- The tax relief for individual and dependent relatives, unchanged since YA 2010, is proposed to be increased from RM9,000 to RM12,000, effective from YA 2027.
- Individual Income Tax Rates Adjustment
- The individual taxable income bands are proposed to be revised as follows effective from YA 2027:
- • RM70,001–RM100,000: tax rate reduced from 19% to 18%.
- • RM100,001–RM150,000: new tax band introduced at 24%, reduced from the existing 25% rate.
- • RM150,001–RM400,000: tax rate remains at 25%.
- • RM600,001–RM1,000,000: tax rate remains at 28%, with the upper limit revised from RM2,000,000 to RM1,000,000.
- • Above RM1,000,000: tax rate of 30% applies, revised from the previous threshold of above RM2,000,000.
- Health and Well-Being Relief Including Postnatal Care
- From YA 2027, the individual income tax relief for medical treatment is proposed to be reclassified as Health and Well-being relief, with the overall relief limit maintained at RM10,000. The scope of relief is proposed to be expanded to include the following expenses:
- Postnatal care services provided by a confinement centre or qualified individual, limited to RM3,000.
- Breastfeeding equipment for children aged 2 years and below, paid for by self or spouse, limited to RM1,000.
- The existing individual income tax relief for breastfeeding equipment will be merged into the Health and Well-being relief.
- Broader Relief for Care of Parents and Grandparents
- From YA 2027, individual income tax relief for expenses incurred in caring for parents and grandparents at home, day care centres and residential care centres is proposed to be expanded to cover all types of care expenses, rather than being limited to medical care, subject to the existing overall relief limit of RM8,000.
- Claims must be supported by a written declaration from the carer (excluding the taxpayer, spouse or children) or a copy of the carer’s work permit, together with receipts. Verification by a registered medical practitioner will no longer be required to support these claims.
- Sports-Related Lifestyle Relief for Sports Shoes
- From YA 2027, the individual income tax relief for sports-related lifestyle expenses is proposed to be expanded to include the purchase of sports shoes, limited to RM300, for self, spouse, child or parents. The overall relief limit remains at RM1,000.
- Reclassified Education and Skills Training Fees Relief
- From YA 2027, individual income tax relief for education fees and skills courses under lifestyle relief is proposed to be merged and reclassified as Education and Skills Training Fees relief, with the overall relief limit remaining at RM7,000. The revised scope is as follows:
- Fees for self to undertake courses or studies recognised by any regulatory agency, at Certificate, Diploma, Bachelor’s, Master’s or Doctor of Philosophy level in any field, at a local institution or professional body in Malaysia recognised by the Government of Malaysia or approved by the Minister of Finance.
- Fees incurred for self or spouse to undertake upskilling or self-enhancement courses or studies in Technical and Vocational Education and Training (TVET), recognised by the Director General of Skills Development under the National Skills Development Act 2006.
- Fees incurred for courses, training, skills and self-enhancement classes unrelated to employment for self or spouse; or courses, training, classes or tuition in Science, Technology, Engineering and Mathematics (STEM), arts, languages and religion for children.
- Lifestyle Relief for AI Subscriptions and Pet Care
- From YA 2027, the individual income tax relief for lifestyle expenses is proposed to be expanded to include:
- Subscription expenses for Artificial Intelligence (AI) software and applications for personal use, spouse or child.
- Pet adoption costs from registered animal shelters.
- Registered veterinary services for pet vaccination and spaying or neutering procedures.
- The overall limit for individual lifestyle tax relief remains at RM2,500, including the proposed expanded scope.
- Expanded SOCSO Contribution Tax Relief
- From YA 2027, individual income tax relief for SOCSO contributions is proposed to be revised as follows:
- The existing tax relief of RM350 is expanded to cover mandatory employee contributions to the Self-Employment Social Security Scheme (LINDUNG KENDIRI) for three mandatory sectors: passenger transport, goods or food transport, and hawkers.
- An additional tax relief of up to RM150 is provided for voluntary employee contributions to the Non-Employment Injury Scheme (LINDUNG 24) and the 17 non-mandatory sectors under LINDUNG KENDIRI, as listed under the Self-Employment Social Security Act 2017 [Act 789].
- Tax Deduction for Cash Contributions to the School Public Contribution Fund
- From YA 2027, the School Public Contribution Fund (Tabung Sumbangan Wang Awam Sekolah — TSUWAS) is proposed to be expanded to cover administrative and operating expenses, repairs and maintenance, procurement of equipment and school programmes for students.
- Applications to establish of TSUWAS must be submitted to the Inland Revenue Board of Malaysia (IRBM) with endorsement from the Minister of Education (MOE). The fund will be jointly administered by the school, Parent-Teacher Association (PTA) or Alumni Association with monitoring by MOE based on guidelines to be determined.
- Extension of Individual Income Tax Relief for Tourism Expenses
- To promote domestic tourism, tourism tax relief of up to RM1,000 on entrance fees is extended to year of assessment 2027
- Entrance fees includes:
- Tourist attractions such as museums, zoo, theme parks, national parks, marine parks and geoparks.
- Cultural and arts programmes.
STAMP DUTY
- Stamp Duty Exemptions for First Residential Home Purchases
- The Government has proposed that the stamp duty exemption for the purchase of first residential home be revised as follows:
- Homes priced up to RM500,000
- 100% stamp duty exemption on loan agreements and instruments of transfer
- Home priced up to RM750,000
- 100% stamp duty exemption on the first RM500,000 of the home price; and
- 50% stamp duty exemption on the remaining home price exceeding RM500,000 up to RM750,000.
- These proposed exemptions apply to loan agreements and instruments of transfer relating to sale and purchase agreements executed from 1 January 2027 to 31 December 2030.
- Stamp Duty Exemption for Revival of Abandoned Housing Projects
- To achieve zero abandoned housing projects by 2030, the Government has proposed to reintroduce a 100% stamp duty exemption on loan agreements and instruments of transfer executed by rescue contractors, developers and original buyers in relation to the revival of abandoned housing projects certified by the Ministry of Housing and Local Government.
- This proposed exemption applies to loan agreements and instruments of transfer executed from 1 January 2027 to 31 December 2030.
- RM10 Stamp Duty for Loan and Financing Agreements under the CAKNA Scheme
- The Government has proposed that stamp duty exceeding RM10 on principal loan or financing agreements executed by MSMEs and small contractors under the CAKNA Scheme be remitted as follows:
- CAKNA I: extend the remission for two years, for agreements executed from 1 January 2029 until 31 December 2030.
- CAKNA II: reintroduce the remission of stamp duty exceeding RM10 for agreements executed from 1 January 2027 until 31 December 2030.
- Stamp Duty Remission on Mid-Tier Companies’ Surplus Credit Agreements
- Under the Supplier Financing Programme, stamp duty exceeding RM10 is proposed to be remitted on second-tier agreements executed between Mid-Tier Companies (MTCs) and financial institutions for excess credit facilities for early payment to MSME suppliers, subject to both conditions:
- The MSME supplier has fulfilled its contract to supply goods or services to the MTC; and
- The MSME supplier is not a parent company, subsidiary or related company of the MTC.
- The remission applies to second-tier agreements executed from 1 January 2027 to 31 December 2030. First-tier credit facility agreements remain subject to stamp duty at rate of 0.5%.
- RM10 Stamp Duty on P2P Loan Agreements
- To encourage Micro, Small and Medium Enterprises (MSMEs) to obtain alternative financing through peer-to-peer (P2P) platforms, the Government has proposed to grant remission of stamp duty exceeding RM10 on P2P loan or financing agreements executed between MSMEs and investors.
- This proposed remission applies to loan or financing agreements executed from 1 January 2027 to 31 December 2030.
- Full Stamp Duty Exemption for Opening Savings and Current Accounts
- The Government has proposed a 100% stamp duty exemption for opening of saving and current accounts effective from 1 January 2027.
- Stamp Duty Exemption for GSH and JS-SEZ Intercompany Loan Agreements
- From 1 January 2027, companies under the Global Services Hub (GSH) incentive that manage treasury and funds will be exempt from stamp duty on intercompany loan agreements. The same exemption will also apply to these activities under the Johor-Singapore Special Economic Zone (JS-SEZ) package.
- Maximum Limit of Stamp Duty for Loans to Purchase or Construct Malaysian Ships
- The Government has proposed that the maximum stamp duty on loan or financing agreements for the purchase or construction of Malaysian ships be capped at:
- RM2,000 for loans or financing amounting up to RM100 million; and
- RM5,000 for loans or financing exceeding RM100 million.
- This applies to loan or financing agreements executed from 1 January 2027.
- Review of Stamp Duty on Foreign Currency Loan or Financing Agreements
- To enhance access to domestic financing, the Government has proposed to cap the stamp duty on foreign currency loan or financing agreements from banks in Malaysia as follows:
- RM2,000 for loans or financing up to RM100 million; and
- RM5,000 for loans or financing exceeding RM100 million.
- The proposed stamp duty limits apply to loan or financing agreements executed from 1 January 2027.
OTHERS
- Expansion of Sumbangan Asas Rahmah (SARA) Purchases and Participation by Small Grocery Stores
- The Government has agreed to allow SARA to be used to purchase fresh produce and wet-market goods at 216 farmers’ markets or tamu operated under FAMA nationwide.
- Minimum Wage Increased to RM2,000 Effective June 2027
- The Government has agreed to increase the minimum wage from RM1,700 to RM2,000, effective June 2027
- Micro, small and medium enterprises (MSMEs) with sales revenue below RM50 million are exempted.
- Minimum Wage of RM2,500 for Semi-Skilled Jobs and Graduates
- The reform addresses skilled workers’ wages that remain out of line with their qualifications, beyond the income floor provided by the general minimum wage.
- The Government will reform the employee income framework by introducing a starting minimum wage of RM2,500 per month for semiskilled jobs and graduates.
- RM160 Million Package for E-Hailing and P-Hailing Workers
- While awaiting the finalisation of the gig-worker arrangements, the Government and Grab have agreed to jointly fund a RM160 million package starting in 2027 to increase net income and improve the welfare of e-hailing and p-hailing workers.
- The package covers:
- An increase in minimum income rates;
- Assistance with vehicle maintenance and insurance costs;
- SOCSO contributions; and
- EPF contributions
- SOCSO Matching Contribution Incentives for E-Hailing, P-Hailing and Self-Employed Workers
- The Government will offer a 35% PERKESO matching contribution incentive to e-hailing and p-hailing workers. The incentive will increase to 50% if the platform company also contributes towards the workers’ contributions.
- In addition, the Government will offer a 70% PERKESO matching contribution incentive to more than 200,000 self-employed persons across 17 non-mandatory sectors, excluding e-hailing and p-hailing workers.
- EPF Matching Contributions for E-Hailing and P-Hailing Drivers
- To encourage retirement savings among e-hailing and p-hailing drivers, the Government is offering an EPF matching contribution incentive of up to RM600 per year or RM6,000 over a lifetime.
- Zakat Payments Directly From EPF Shariah Savings Dividends
- EPF members who choose Simpanan Shariah can now pay zakat directly from their dividends, in line with the facilities available at Permodalan Nasional Berhad (PNB) and Lembaga Tabung Haji.
- Monthly EPF Withdrawals Under the i-Emas Scheme
- EPF members who reach the aged 55 and 60 may opt for the i-Emas scheme for monthly withdrawals, allowing their remaining savings to continue earning dividends.
- Higher Bankruptcy Threshold and Expanded SecondChance Measures
- Starting from 2027, the bankruptcy threshold will be increased from RM100,000 to RM150,000.
- To accelerate discharge from bankruptcy, the Dasar Peluang Kedua Prihatin will be expanded to cover primary caregivers of family members with disabilities, chronic patients, senior citizens, gig workers and individuals without fixed income.
- Automatic discharge as early as three years under Section 33C of the Insolvency Act will continue to be strengthened to expedite the discharge of bankrupt individuals who meet the requirements.
- EPF Savings for MediAsas Premiums
- The Government will launch the affordable MediAsas scheme starting January 2027. Under this plan, hospital charges will be standardised by type of diagnosis and treatment to ensure cost predictability and control.
- EPF members below the age of 55 will be allowed to pay MediAsas premiums through Akaun Sejahtera.
- Proposed E-Commerce Bill and Review of Enforcement Measures
- The Government is examining legislative and enforcement measures to protect local MSMEs from unfair competition involving foreign ecommerce companies and to ensure goods purchased by the public are safe.
- An E-Commerce Bill will be tabled at the next parliamentary meeting to strengthen the accountability of online platforms and sellers.
- Work Permission for Spouses of Category I Employment Pass Holders
- Effective 1 January 2027, spouses of expatriates holding Dependant Passes under Category I Employment Pass will be allowed to work in Malaysia, subject to prescribed conditions.
- Additional Stay for Existing (Digital Economy) DE Rantau Nomad Pass Holders
- Existing DE Rantau Nomad Pass holders who have reached the two-year limit will be given an additional two years to continue staying and working remotely in Malaysia, subject to prescribed conditions.
- Malaysian ASEAN Business Entity (MyABE) Status to Facilitate Regional Expansion and Talent Mobility
- The Government has proposed the introduction of MyABE status to support Malaysian companies in expanding across ASEAN. The Securities Commission Malaysia and TalentCorp will collaborate to facilitate the initial Employment Pass application process for listed MyABE companies, with a targeted approval timeline of five working days.
- Enhancing Education Support for Students and Families
- The Government has proposed to increase the Bantuan Awal Persekolahan from RM150 to RM200 for each student effective for the 2027 school session.
- The Government has agreed to provide a living allowance of RM2,500 to Form Six students, aligning their allowance with that of matriculation students.
- FlySiswa MADANI 2027 Flight Ticket Assistance
- The government has proposed to increase the FlySiswa MADANI flight ticket assistance for 2027 from RM400 to RM500. The proposed increase is expected to benefit more than 60,000 students at public higher education institutions (IPTAs).
- BUDI Belia Programme to Promote Youth Volunteerism
- The Government has proposed the BUDI Belia programme to encourage youth volunteerism. Under the programme, youths who complete the required volunteer hours with selected non-governmental organisations (NGOs) will receive an e-wallet incentive of RM100.
- Minimum Monthly Pension Increased from RM1,000 to RM1,350
- The Government has proposed to increase the minimum monthly pension from RM1,000 to RM1,350. The proposed increase is expected to benefit nearly 59,000 pensioners, Malaysian Armed Forces (ATM) veterans, and derivative pension recipients.